Booking Date vs. Accrual Period: When Did You Really Earn It?
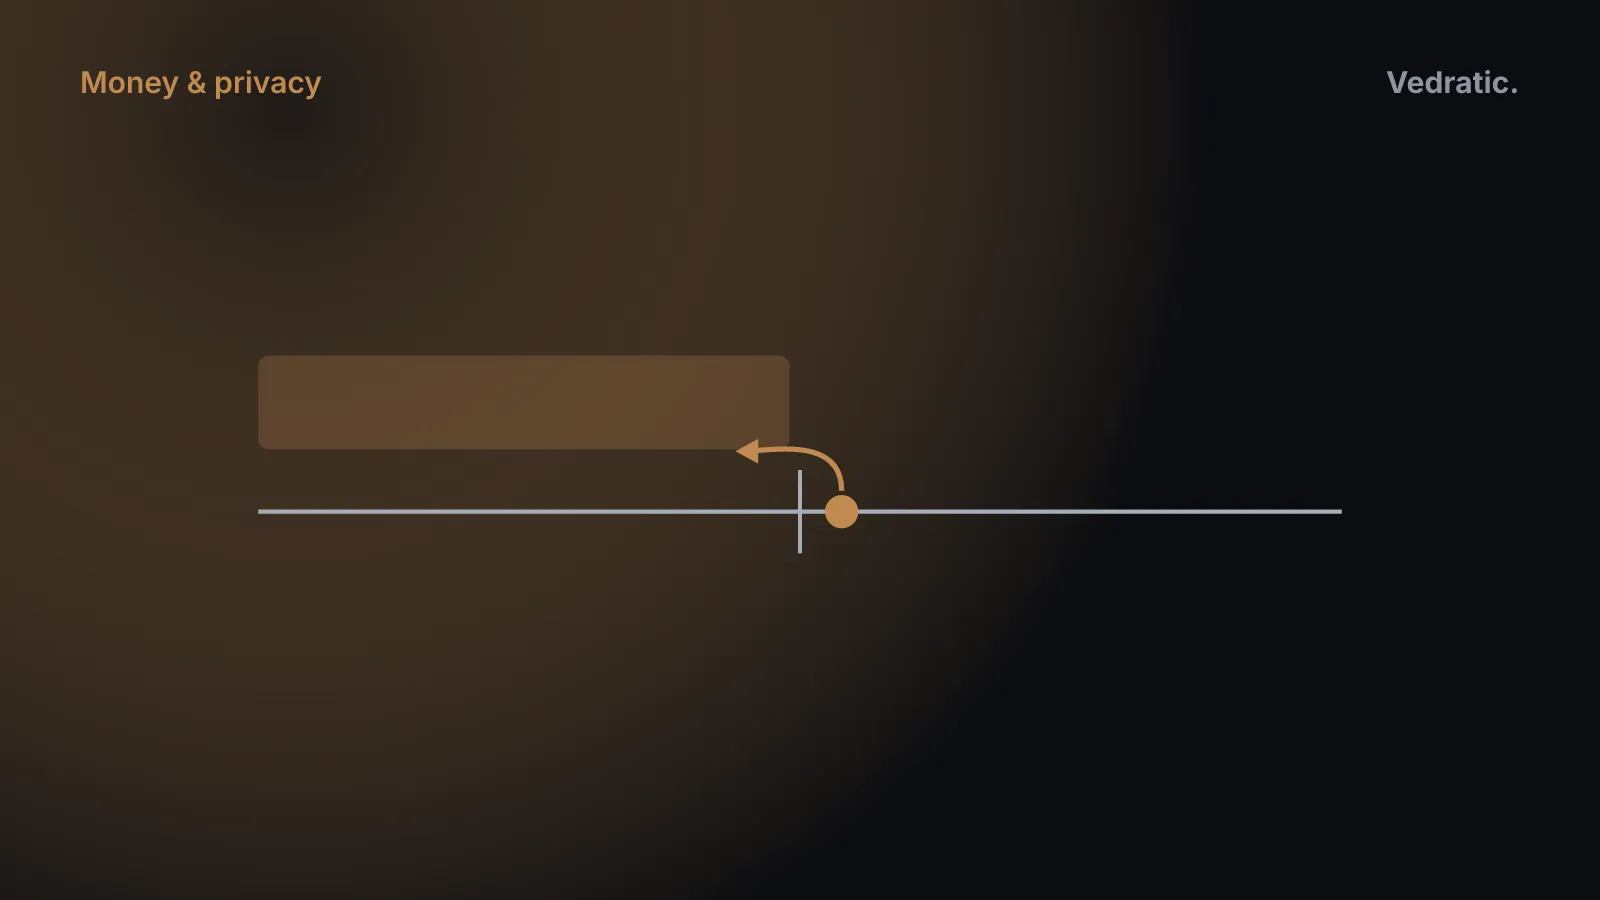
Open almost any budgeting app and look at your monthly income over a year. There’s a good chance you’ll find a month with two salaries and a month with none. You didn’t get a bonus, and you weren’t unpaid. Your employer simply paid February’s salary on March 1st because the last day of February fell on a weekend.
It’s a tiny calendar accident, and it wrecks two months of reports: one looks unusually rich, the other looks like a crisis, and your savings rate swings wildly for no real reason. When we designed Ahorreo, we decided that this wasn’t a user error and wasn’t the bank’s fault either. It’s a modelling problem: the date a bank books a transaction and the month it belongs to are two different things.
Two Dates, Two Jobs
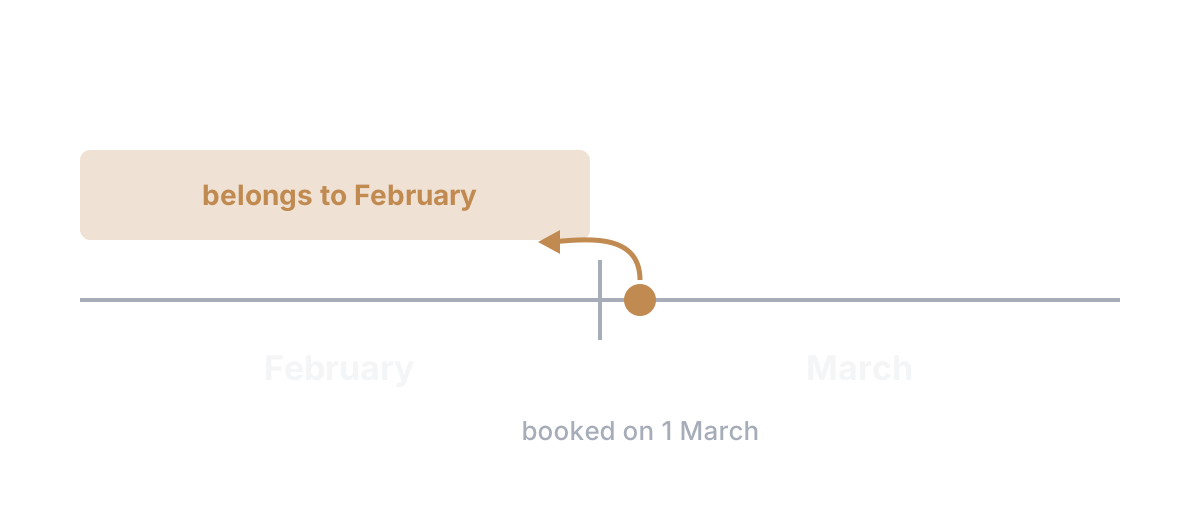
Every transaction in Ahorreo carries two pieces of time information:
- The booking date: when the bank recorded it. It comes from the statement and never changes.
- The accrual period: the month it belongs to in your reports. By default it’s the month of the booking date.
Monthly reports, budgets and savings rates are grouped by accrual period. Balance reconciliation, on the other hand, always uses the booking date — your bank knows nothing about accrual periods, and a balance on a given day is a fact about that day.
The transaction list stays honest
The list of transactions always shows the real date the money moved. When the accrual period differs, it says so, right next to the date. Nothing is hidden or rewritten; the app just files it in the right month.
Case 1: Salaries
For income series marked as payroll, Ahorreo applies a simple default: a payment on or after the 20th belongs to that month; a payment on or before the 10th belongs to the previous month; anything in between stays in the month it was paid. The rule is per series, because not every employer pays on the same schedule, and any individual payment can be corrected by hand.
It sounds almost trivial, and that’s the point. With it, twelve salaries fall into twelve months, and the December that carries both the regular salary and an extra payment shows both — which is what actually happened.
Case 2: Credit Cards
Credit cards produce the same distortion in reverse. You buy something on March 28th; the card’s cycle closes, and the total is charged to your current account on April 1st. If you only import your current account, all you see is one opaque lump in April.
Ahorreo treats a credit card with a billing cycle as its own account. Purchases are transactions of the card, dated when you made them — March, in this example, because that’s when you decided to spend. The lump-sum charge on your current account becomes an internal transfer from your current account to the card, matched automatically against the cycle it settles. It’s not spending, because the spending already happened when you bought things.
When the cycle doesn’t add up
Real life isn’t always tidy: deferred payments, or a refund that lands in the next cycle, can make a charge differ from the sum of its cycle. When that happens, Ahorreo says so instead of forcing a match. A purchase that doesn’t fit any cycle is reported rather than quietly disappearing.
Why Not “Payday to Payday” Months?
A popular alternative is to redefine the month itself: your month runs from payday to payday. We considered it and rejected it. It shifts every period to fix one case, complicates every aggregate, every budget and every chart label, and still doesn’t fix credit cards. Assigning an accrual period per transaction fixes both cases without touching the calendar at all.
The Same Idea, Everywhere
Once you have the concept, it shows up in more places. A refund belongs with the purchase it reverses, so the month of the purchase returns to zero — in both the report and the budget. A mortgage payment is split into interest, which is an expense, and principal, which is just money moving from your current account into the home you own. We cover that split, and what it means for shared property, in Household or my share?
All of these are the same principle: your reports should describe your economic life, not your bank’s processing calendar. The bank’s dates are kept exactly as they are, for reconciliation and for your records. The month a transaction belongs to is a separate, visible, correctable fact — and it’s the one your budget should be built on.
The amounts themselves are integers, for a related reason: why money should never be a float. And the mortgage calculator shows the interest–principal split for any loan, without importing anything.
This article explains how our software works and the maths behind it. It is not financial, tax or legal advice: for decisions about your own money, check with a qualified professional.